WarBrief Live | October 6, 2026 | Market Explainer
Updated October 18, 2026 — record weekly attack tempo pushes Hormuz war-risk premiums back toward crisis levels.
Latest update — October 18, 2026
Attacks on commercial shipping have reached their highest weekly level since the Iran war began. UK Maritime Trade Operations data, analysed by BBC Verify, shows 12 vessels reported attacks between October 5 and 11 — ten inside the strait itself, one in the Arabian Gulf and one in the Gulf of Oman — up from 10 the previous week. Six vessels were struck on October 11 alone, the highest single-day total of the war, and UKMTO has logged further attacks since, including a tanker struck by an unknown projectile off Saudi Arabia on October 17.
The mine threat returned over the weekend. On October 17, the navy of Iran’s Revolutionary Guard Corps said two supertankers, each carrying about 2 million barrels of crude, caught fire after striking naval mines in the strait while using routes Tehran calls “unauthorised” — see our breaking coverage of the incidents. The claims have no independent confirmation, and Washington is pushing back: US Central Command chief Admiral Brad Cooper said on October 16 that “the Strait of Hormuz is controlled by the United States and our regional partners, not Iran, and it remains open for business,” adding that about 400 merchant vessels had transited the strait in the previous seven days (Anadolu Agency).
Insurance pricing is following the violence back toward crisis levels. Brokers told the Financial Times last week that additional war-risk premiums for Gulf transits now run at 6% to 10% of hull value per voyage — as much as $20 million for a single supertanker trip — against roughly 0.25% before the war (Insurance Business). One trade-publication analysis puts the pre-war norm at 0.15–0.25% and cites market indications of 7.5% to 12.5% ahead of September’s renewed US-Iran exchanges — at 10%, a $150 million tanker pays $15 million for one passage instead of roughly $375,000 (The National). Reinsurer Howden Re estimates the conflict could generate $2–3 billion in war, terror and political-violence claims against a global annual premium pool of only $1.5–2 billion — and regards the repricing of the marine war-risk baseline as likely permanent.
Traffic is thinning as the risk reprices. Kpler counted 131 crossings in the week ended October 14, down from 176 the week before, and about 12.6 million barrels a day of oil passed through the waterway on October 13, down from 15 million at the end of September. Exporters increasingly rely on a shuttle system — smaller tankers ferrying crude through the strait to larger vessels waiting in the Gulf of Oman via a route close to Oman’s coast that Iran also calls unauthorised (The Vibes); see our explainer on the US-protected Omani corridor. Iran’s naval commander has meanwhile warned that vessels switching off their tracking systems will be treated as “hostile,” according to Iranian media reports.
Latest update — October 9, 2026
The tempo of attacks has kept rising. Reuters reported on October 7 that at least 12 tankers — oil, LNG and LPG carriers — were attacked around the Strait of Hormuz in the week of September 28 to October 5, citing three maritime security sources: the highest single-week total since the Iran war began in late February. The UN’s International Maritime Organization logged nine of the incidents.
On October 5, the Panama-flagged tanker On Peace was struck by an unknown projectile in the strait; the incident was reported on October 6. Twelve of the 19 crew were injured — 11 of them Indian nationals — and were evacuated with Oman’s help to Khasab for treatment. India’s foreign ministry condemned the attack. No group has claimed responsibility.
On October 7–8, a tanker was struck by multiple projectiles 59 nautical miles north of Madinat ash Shamal, off Qatar’s northern coast. Casualties were reported, though no number was given, and neither the ship nor the attacker was identified. It was the first reported strike deep inside the Gulf in about a month.
Iranian state broadcaster IRIB claimed on the night of October 8 that several heavy explosions in the southern passage may have been tankers striking naval mines on “unauthorized” routes. No vessel names, casualty figures or damage details were given, and the UK maritime agency UKMTO has published no Thursday incident — this remains an unconfirmed claim, not a confirmed fact.
The shipping data is stark. Kpler recorded seven vessel transits on Tuesday, October 6 — the lowest daily figure since July 23 — and ten on Wednesday, well short of the 20-plus on Sunday and Monday. Crude crossing the strait fell 27% from the previous week’s wartime high to at least 10.1 million barrels a day, just 74% of the pre-war level.
Premiums have followed. Marsh’s global head of marine, Marcus Baker, now puts Hormuz war-risk premiums at 3–10% of hull value per transit — $3 million to $10 million on a $100 million tanker — while Reuters, citing four industry sources, reported a 6–9% range in late September. VLCC day rates from the Gulf to Asia have hit records near $1.2–1.4 million per day, with Brent crude around $104–105 a barrel on October 8.
Diplomatically, Iran’s foreign minister Abbas Araghchi says Washington’s response to Tehran’s seven-day plan to reopen the strait is under review, and an answer will come “within days.”
The Strait of Hormuz is still moving oil, but every tanker that crosses it now pays a war surcharge for the privilege. With at least seven vessels struck since September 28, insurers have turned the strait into one of the most expensive waterways on earth to insure — and that cost quietly lands in fuel, freight, and grocery bills. This war risk insurance explainer breaks down how the mechanism works, who actually pays the premium, and why shipping stays expensive even when crude keeps flowing.
Key Takeaways
- War risk insurance is a separate marine policy covering damage from warlike events — missiles, drones, mines, terrorism, piracy — that standard hull policies exclude.
- Vessels entering Joint War Committee “listed areas” must pay Additional War Risk Premiums (AWRP), priced as a percentage of hull value; Hormuz quotes have risen to several times their pre-war levels.
- Shipowners pay the base war-risk cover; charterers reimburse the additional premium under widely used war clauses such as CONWARTIME 2013 — and those costs flow into freight rates.
- Despite the attacks, Middle East crude exports topped pre-war levels on several days in late September, so the insurance surcharge, not a supply stop, is what keeps shipping costs elevated.
- One line disclaimer: this article explains insurance mechanics and market prices — it is not financial advice.
Latest update — October 11, 2026
The cycle continued this week. Iran reported hitting a tanker in the Strait of Hormuz, and shipping through the strait remains severely disrupted, Gulf News reported on October 10. Every new strike feeds the pricing mechanism described above: underwriters reprice hull and cargo cover on the next voyage, premiums flow into freight rates, and freight rates flow into the fuel and food prices at the end of the chain. Our explainers on Bab el-Mandeb vs the Strait of Hormuz and why diesel prices rise during war were both updated this week with the latest tanker-attack data.
What happened in the Strait of Hormuz this week?
Attacks on commercial shipping in and around the Strait of Hormuz have continued into October. Shipping intelligence firm Marisks reported at least seven incidents in the strait, including the very large crude carrier Kazimah III, which was struck on October 1 by an unknown projectile and caught fire while operating in the strait; all crew were reported safe, Reuters reported on October 5, 2026.
The United Kingdom Maritime Trade Operations (UKMTO) agency has reported at least one attack a day in the Strait of Hormuz or the Gulf of Aden since October 2. On October 4, UKMTO published a notice that the Liberia-flagged aframax tanker Lipsi, managed by Dynacom and only delivered on August 24, 2026, had been struck by an unknown projectile in the strait, damaging its engine room. The US-led Joint Maritime Information Center listed up to four attacks in the strait in the 72 hours from October 2 to October 4, Riviera Maritime Media reported.
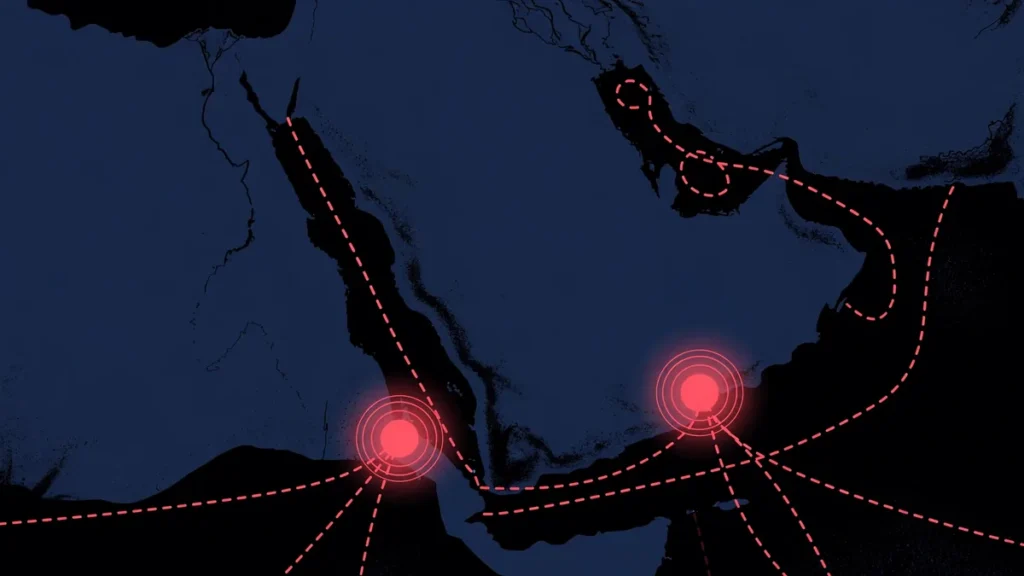
The violence has not stayed confined to Hormuz. Explosions were also reported near the tanker Chrystal Sky in the vicinity of the Bab el-Mandeb strait off Yemen’s coast, one detonation occurring roughly 100 metres from its starboard side, amid Yemen’s widening offensive against the Houthis. The vessel continued its voyage undamaged.
At the same time, oil is still flowing. Provisional data from ship-tracking firm Kpler showed Middle East crude exports above pre-war levels — between 19.5 million and 22.5 million barrels per day — on September 24 and again between September 27 and 29. Before the Iran war began on February 28, 2026, exports averaged about 18 million barrels per day. The paradox of full flows and rising danger is exactly why insurance, not cargo volume, is now the story: the strait that handled roughly 125 large commercial vessels a day and some 20 percent of the world’s daily crude oil and LNG supply has become a “kill box,” in the phrase Marisks used to describe an engagement area where weapons may lock onto any radar signature inside it.
What is war risk insurance?
War risk insurance is a specialized marine insurance policy that covers physical damage to a vessel caused by war and warlike events — the things a standard hull and machinery policy deliberately excludes. Where an ordinary policy covers storms, collisions, and mechanical failure, a war-risk policy covers damage from missile and drone strikes, mines, terrorism, piracy, and military seizure, as Argus Media explains. It is distinct from protection and indemnity (P&I) cover, which handles liability to third parties, crew, and pollution — war-risk cover protects the ship itself and its machinery.
The reason it exists as a separate product is simple: wars are unpredictable and potentially catastrophic, and no ordinary underwriter can price them into a general policy without making everyday shipping unaffordable. War risks therefore get their own policy, their own clauses, and their own premiums — and the premium is only really charged when a ship goes somewhere dangerous.
That “somewhere dangerous” is formally defined. The International Underwriting Association of London and the Lloyd’s of London insurance market’s Joint War Committee (JWC) publish a list of “listed areas” — waters where extra precautions apply. Those areas currently include parts of the Black Sea, the Middle East, Africa, and South America. For waters deemed especially dangerous, insurers demand Additional War Risk Premiums (AWRP) on top of the standard war-risk cover. The Bab el-Mandeb strait and the Russian and Ukrainian sectors of the Black Sea are among the areas attracting AWRP, and without paying that extra premium, vessels are simply not insured to pass through them.
How does war risk insurance work?
The mechanics are straightforward, even if the pricing is not. A shipowner buys a war-risk policy as a standard part of the vessel’s insurance, usually renewed annually. That base cover is priced against a benign world — a ship sitting in safe waters. The moment the vessel is ordered into a listed area, underwriters attach an additional premium for that specific voyage, calculated as a percentage of the ship’s Hull and Machinery Value: the total insured worth of the vessel’s structure, engines, and equipment.
Rates move with the news, often daily. Before the latest round of strikes in the Middle East, AWRP for the Gulf stood at around 0.15 to 0.2 percent of hull value, according to brokers quoted by Argus Media in March 2026; after the strikes, regional rates surged to about 1 percent. By mid-September, two major brokers told Reuters that premiums for a seven-day Hormuz voyage had risen to 0.5 percent of hull value from 0.25 percent before the latest attacks — on a $100 million tanker, an extra $250,000 per voyage. Market commentary in late September put effective Hormuz quotes in a wide band, from roughly 1.5 percent of hull value upward depending on the vessel, its flag, its ownership, and its exact routing. On a $150 million VLCC hull, even a 1.5 percent rate means about $2.3 million of additional premium for a single transit, versus roughly $150,000 in normal conditions.
So who actually pays? The shipowner arranges and pays the base war-risk cover. The additional premium, however, is normally pushed to the charterer — the company that hired the ship and ordered it into the dangerous area. Widely used industry war clauses such as CONWARTIME 2013 and VOYWAR 2013 state this explicitly: charterers reimburse owners for any additional insurance premiums reasonably incurred as a consequence of orders to trade in war-affected areas, with the Hellenic Shipping News’s legal guidance confirming that charterers bear the AWRP for listed-area calls. Real charterparty contracts filed with regulators repeat the same formula — owners pay the basic annual war-risk contribution; the charterer pays the full additional premium for listed-area voyages.
There is a reason the charterer accepts this. In a time charter, the charterer decides where the ship goes; in a voyage charter, it decides the ports. The party giving the orders carries the extra insurance cost. That cost then flows into the freight rate the charterer charges for the cargo — and from there into the price of crude, refined products, and ultimately the goods consumers buy. As Vortexa analyst Ioannis Papadimitriou told Fortune in September, Hormuz insurance premiums had climbed to about 10 percent of the assets aboard from 0.5 to 1 percent before the war, “and those premiums are then passed down for the charterers to pay.”
By the numbers: Hormuz premiums in 2026
| Metric | Figure | Source |
|---|---|---|
| Incidents in/around Hormuz since Sept 28 | At least 7 vessels struck | UKMTO via Wall Street Journal; Marisks via Reuters (CONFIRMED) |
| Attack frequency since Oct 2 | At least one attack/day in Hormuz or Gulf of Aden | UKMTO via Reuters (CONFIRMED) |
| Middle East crude exports, Sept 24, 27–29 | 19.5–22.5 million bpd (above pre-war) | Kpler via Reuters (REPORTED — provisional data) |
| Strait’s pre-war share of global supply | ~125 large vessels/day; ~20% of world crude oil and LNG | Reuters, Oct 5, 2026 (REPORTED — single source) |
| AWRP, Mideast Gulf, early March 2026 | 0.15–0.2% of hull value → ~1% after strikes | Insurance brokers via Argus Media (REPORTED) |
| AWRP, seven-day Hormuz voyage, Sept 12 | 0.5% of hull value (from 0.25%) = ~$250,000 on $100M tanker | Two major brokers via Reuters (REPORTED via secondary) |
| AWRP, Hormuz, late September 2026 | ~1.5% of hull value and up; crude tankers ~5–5.75%, product tankers ~7–9% in some snapshots | Market reports via LinkedIn/ainvest (REPORTED — single secondary sources) |
| Gulf shuttle-run cost | $30–40M per run; ~$15–20/barrel extra excl. insurance | WSJ via Seoul Economic Daily, Oct 6, 2026 (REPORTED via secondary) |
| VLCC charter rate (pre-war → late Sept) | ~$231,400/day → over $1.2M/day | WSJ via Seoul Economic Daily (REPORTED via secondary) |
Caveat: CONFIRMED figures are corroborated by two or more reputable outlets; REPORTED figures come from a single source or a single data provider and should be treated as indicative.
Hormuz crisis: background and timeline
War risk premiums at Hormuz are a barometer of a war that has been escalating since the spring of 2026. The trajectory matters because it explains why premiums stay high even on days when oil flows freely.
- February 28, 2026: The US-Israeli war with Iran begins. Middle East crude exports had averaged about 18 million barrels per day between March 2025 and February 2026.
- March 2026: Several P&I clubs suspend shipowners’ war-risk insurance in the Middle East, and brokers report AWRP in the Mideast Gulf surging from 0.15–0.2 percent of hull value to around 1 percent ahead of US and Israeli strikes on Iran, according to Argus Media.
- July 20, 2026: Dynacom confirms its tanker Kavomaleas was struck by two projectiles of unknown origin off Oman; a second Dynacom vessel, the VLCC Acheloos, is also confirmed struck.
- September 12, 2026: Two major brokers tell Reuters that war-risk premiums for a seven-day Hormuz voyage have doubled to 0.5 percent of hull value.
- Late September 2026: Market commentary puts effective Hormuz quotes at roughly 1.5 percent of hull value and higher; VLCC charter rates on Gulf routes exceed $1.2 million a day.
- September 24, 27–29, 2026: Kpler data shows Middle East crude exports above pre-war levels at 19.5–22.5 million barrels per day.
- October 1, 2026: VLCC Kazimah III struck by an unknown projectile in the strait; fire onboard; crew evacuated safely.
- October 2–4, 2026: UKMTO and the Joint Maritime Information Center record up to four attacks in 72 hours; on October 4 the aframax Lipsi is struck in the engine room.
- October 4, 2026: Explosions reported near the tanker Chrystal Sky near the Bab el-Mandeb strait; IRGC Navy radio broadcasts a warning to ships not to use the strait’s “south corridor,” with the Wall Street Journal quoting the message as “Don’t trust U.S. Navy and don’t use south corridor at all and don’t put your life in danger.”
Why the Hormuz war-risk surcharge matters
War risk insurance is the quiet mechanism that keeps energy flowing in wartime — and the reason it never gets cheap again quickly. Without it, lenders and charterers will not finance or hire a tanker into a listed area at all: “is war risk insurance mandatory?” is a question freight specialists answer with no in law but effectively yes in practice, because charterers and lenders typically require it for high-risk voyages. It is, in effect, the toll that lets the world’s most important oil artery keep functioning under fire.
It also explains the lag between geopolitical news and consumer prices. Premiums are set voyage by voyage, and underwriters reprice risk on incidents, not headlines. That is why freight stays elevated even as oil flows recover: Kpler data can show exports above pre-war levels while a single drone funnel strike, like the one reported on October 3, keeps underwriters pricing each transit as a potential total loss. Insurance costs, as one market analyst noted in September, are quoted gross of the headline freight rate — benchmarks like Platts’s tanker assessments exclude additional war-risk premiums — so the record rates celebrated in markets are the revenue number before subtracting the fastest-rising cost in the business.
Different perspectives on the Hormuz insurance spike
Underwriters see the strait as a pricing problem with no ceiling: if Iranian forces are firing missiles into a predetermined engagement area where “physical presence within the engagement zone at the relevant time could itself represent the primary exposure,” as Marisks wrote, then the risk attaches to the voyage itself, not the ship’s flag or cargo. Premiums therefore stay punitive regardless of diplomacy.
Shipowners and Gulf producers take the opposite view: the toll is simply the price of keeping oil moving. The Wall Street Journal reported that Saudi and other Gulf producers are running high-risk “shuttle runs” — VLCCs loading inside the Gulf and transferring cargo outside the strait — at $30 to $40 million per run, judging that paying the premium beats leaving the oil in the ground.
Iran‘s perspective is that the warning system is the pricing. The IRGC Navy has warned that safe passage exists only through routes it designates, and Rear Admiral Ali Fadavi said on October 4 that captains transiting the southern route have formally objected to it but are forced through by insurance, financial, and liability concerns — while the IRGC Navy warns that vessels on that route may be targeted at any point.
Consumers never see the insurance line item. But when a $2.3 million war-risk premium is added to a single VLCC transit, that cost is amortized across roughly two million barrels of crude and passed down the chain — refiner, distributor, pump, grocery shelf — in prices that react to freight with a lag of weeks.
What the Hormuz surcharge means for US, UK and EU readers
For American, British, and European readers, the Hormuz insurance surcharge arrives as background inflation, not as a headline. Fuel prices are the most direct channel: crude that cost $15 to $20 more per barrel just to move through the shuttle system (excluding insurance, per the Journal) feeds into refinery margins and then into petrol and diesel. European diesel — the fuel of trucking, farming, and delivery fleets — is especially exposed because Europe’s refineries and import routes lean on Middle Eastern crude and product flows.
Groceries and consumer goods follow with a longer delay. Everything that arrives by sea — electronics from Asia, textiles, components — rides on freight rates that are still multiple times their peacetime level on Gulf routes, and war-risk premiums are embedded in those rates. Airline tickets feel it too: jet fuel pricing tracks crude, and aviation war-risk dynamics can mirror shipping’s. The counterpoint is worth remembering: because the physical oil keeps flowing, the price signal is a risk premium, not a shortage premium — which is why it can unwind quickly if underwriters conclude the shooting has stopped, and why it persists stubbornly while strikes continue even one a day.
What to watch next
Watch the Joint War Committee’s listed-areas updates and any broker chatter on AWRP levels: those are the earliest signals that underwriters think the danger is receding or worsening. Watch UKMTO’s daily notices — the attack count since October 2 is the data that moves premiums — and follow our intelligence reporting for more maritime-security analysis. Watch whether P&I clubs that suspended Middle East war-risk cover begin reinstating it, which would signal that professional risk-takers consider the worst over. And watch the October diplomatic track: if talks produce a durable de-escalation, premiums can fall as fast as they rose — but as long as missiles keep entering a “kill box,” the surcharge stays, no matter how many barrels make it through.
Frequently asked questions
What is war risk insurance for cargo?
It is specialized coverage for cargo losses caused by war, terrorism, and civil unrest that standard marine cargo policies exclude. Shipowners’ war-risk policies cover the vessel and machinery; cargo interests buy their own war cover, often via war and strikes clauses added to a standard cargo policy, with surcharges applying when the voyage enters a JWC listed area.
Does war risk insurance cover terrorism?
In most cases, yes — war-risk clauses typically cover damage from missile or drone attacks, mines, acts of terrorism, and piracy, though definitions of what counts as conflict-related damage vary between policies. Terrorism is generally treated as a warlike peril in marine war-risk wordings rather than as an excluded event.
How much does war risk insurance cost in 2026?
It is priced per voyage as a percentage of hull value. For the Mideast Gulf, brokers reported roughly 0.15–0.2 percent of hull value before the 2026 strikes and about 1 percent after; by mid-September a seven-day Hormuz transit was quoted around 0.5 percent, with late-September market references reaching 1.5 percent and higher depending on vessel, flag, and routing. One line to remember: this is market commentary, not financial advice.
Who pays war risk insurance — the shipowner or the charterer?
Both, in practice. The shipowner pays the base annual war-risk cover. Any additional premium triggered by entering a listed area is reimbursed by the charterer under widely used war clauses such as CONWARTIME 2013 and VOYWAR 2013, because the charterer is the party ordering the ship into danger. The charterer then passes that cost into freight rates, so consumers ultimately carry part of the bill.
Why are war risk premiums so high in the Strait of Hormuz?
Because underwriters price incidents, not flows. At least seven vessels have been struck since September 28 — with Marisks describing Iranian missiles being fired into a predetermined “kill box” — and UKMTO has reported attacks at a rate of one a day since October 2. Until the strike rate drops, insurers will keep quoting each transit as a potential total loss, which is why premiums stay elevated even when crude exports run above pre-war levels.
Sources
- Reuters: Middle East crude oil exports exceed pre-war levels but tanker attacks increase (Oct 5, 2026)
- Riviera Maritime Media: Dynacom newbuild Aframax tanker among multiple vessels hit in Strait of Hormuz
- Argus Media: Explainer — War risk insurance and AWRP
- Jalopnik (citing Wall Street Journal): 7 Oil Tankers Attacked In Strait Of Hormuz, As U.S. Official Admits Iran’s Targeting Abilities Keep Improving
- Hellenic Shipping News: War in Ukraine — impact on contractual obligations (CONWARTIME 2013 / AWRP liability)
- SEC (charterparty filing): War Risk Premium clause — charterers reimburse additional war-risk premiums
- Seoul Economic Daily (citing Wall Street Journal): Gulf Producers Pay $40 Million for Risky Hormuz Shuttle Runs (Oct 6, 2026)
[…] the town of Dhubab — including Dhubab airport — and the towns of Bab and Hadeid around the war-risk insurance surcharge hitting shipping near the Bab el-Mandeb strait, the chokepoint through which about 12% of global trade transits. Witnesses reported […]
[…] bill for every voyage through the kill box lands, eventually, at the pump. War-risk insurance premiums for a Hormuz transit have multiplied: hull war cover that ran about 0.25 percent of a […]
[…] to fertilizer — costs that land on household bills and farm inputs. Read our explainer on how war-risk insurance surcharges work for the mechanism that turns distant attacks into price […]
[…] where a Yemenia flight was forced to divert — are a nightmare scenario for insurers and carriers. War-risk premiums and surcharges rise with every confirmed strike, and carriers quietly reroute around threatened airspace even […]
[…] next: War Risk Insurance Explained: The Hormuz Surcharge (2026) — how attacks on shipping turn into the surcharges behind rising […]
[…] The immediate strategic prize is the Bab el-Mandab strait, the narrow gate between the Red Sea and the Gulf of Aden. With traffic through the Strait of Hormuz restricted by the wider US-Iran war, the Red Sea route matters more than ever for energy exports — and any sustained fighting around the strait raises the risk premium on shipping, insurance and fuel. Read our explainer on how war-risk insurance surcharges work. […]
Do you mind if I quote a few of your posts as long as I provide credit
and sources back to your webpage? My blog site
is in the very same niche as yours and my visitors would truly
benefit from some of the information you provide here.
Please let me know if this ok with you. Regards!